Saturday, June 5, 2010

May Employment Report: 20K Jobs ex-Census = Employment-Population Ratio, Part Time Workers, Unemployed over 26 Weeks

[mEDITate-OR:
calculate how much you are loosing by not having "Calculated ([y]our?) Risk"...

First, remember to visit CR's web site for the large view.

Second, you should look at and compare the 2nd and 3rd charts.
Same info, different perspective.
Available ONLY from Jim @ CR.

------------
This graph shows the unemployment rate and the year over year change in employment vs. recessions.
The second graph shows the job losses from the start of the employment recession, in percentage terms (as opposed to the number of jobs lost).
---------
This graph shows the job losses from the start of the employment recession, in percentage terms - but this time aligned at the bottom of the recession.
This graph shows the employment-population ratio; this is the ratio of employed Americans to the adult population.

The number of persons employed part time for economic reasons (some-times referred to as involuntary part-time workers) declined by 343,000 in May to 8.8 million. These individuals were working part time because their hours had been cut back or because they were unable to find a full-time job.
The blue line is the number of workers unemployed for 27 weeks or more. The red line is the same data as a percent of the civilian workforce.
--------
This graph is a favorite of those expecting a huge rebound in employment. The graph is a little complicated - the red line is the three month average change in temporary help services (left axis). This is shifted four months into the future The blue line (right axis) is the three month average change in total employment (excluding temporary help services and Census hiring).
=========

As federal stimulus fades, private hiring falters

[mEDITate-OR:
not see that what looked so good last month...
look very bad this time.

Which only goes to prove that Presidents should NOT make economic predictions.
-------
As federal stimulus fades, private hiring falters
Surge in Census jobs in May masks underlying employment weakness 
 
As the impact of government stimulus fades, job creation will have to come from growth in the private sector. The latest data on the job market weren't encouraging.
----------
Private employers stall hiring in May
U.S. added 431,000 jobs, most of which were for temp census workers
Job creation by private companies grew at the slowest pace of the year in May, even while the hiring of temporary census workers drove overall payrolls up 431,000.
---------
Video:
June 4: Labor Secretary Hilda Solis explains why private businesses are pulling back on hiring in the dismal job market.
===========

Did Fannie and Freddie Cause the Housing Bubble? Part 2

Following the first of Daniel's articles
there started an interesting discussion...
--------
Daniel, even we make some errors. nadezhda below makes another interesting point - for us - you, me and U.S. - that bcuz of their RE loan size limits, it was not possible for FMae&Mac to even make the worst of the large ARMs, AltAs and subprime RE loans. True, that would have been much more true in the Sand State where the cost of housing exploded up above those lending limits. So, you might argue with me that the real reason that FMae&FMac did not make all those bad RE loan was that they COULD not.
But, that does not solve {y}our problem = Who DID make those loans?

And something else for you to consider, Who "services" those bad NAS securitized RE loans? Why the Big Three Bad Banks, of course - BankOAmer is no 1, Chase is no 2 and Wells is no 3. And, while FMae&FMac ARE doing modifications, those banks are not.
Why, Daniel?
Is it bcuz they originate those bad loans, then sold them to "The Suckers", but then kept them for the "servicing" profits?

====
And, Daniel, please take a look at WHO is now being required to buy back some of the worst of the bad loans that were sold to FMae&FMac.

The names most often occurring are, would you believe this, BkOAmer/Countrywide, Chase/WAMU and Wells/Wachovia. As the SNL "Lady" oft said to U.S.: "Isn't that special."

======
While the first point is important, what is also is that there is an OVERstating of the F&F problems by some/many, AND a total ignoring of the NAS - non-agency Securitized - RE loan problems.

Where are THOSE numbers? Jozef and/or Daniel? Show me the money, and/or where IS the beef?
---------

Jozef:
Your response to my first point was to answer the wrong question. We did not ask you to look up GSE numbers for U.S., as you showed U.S. anyone can do that. What we asked was WHAT are the non-agency securizations packages numbers?
For most of the dead zone years when most of the subprime and AltA loans were created, the non-agency RE loans were over 50% of the total RE market, and an even higher number in the Sand States = Cal, Nev, Fla & AZ. 

What ARE the non-agency bad loan number for THOSE state, for those bad loan years?
Go ahead, try to find them!
=========
Josef, do you really find it troubling that "fraudulent" RE loan practices by Countrywide, WAMU and Wichovia, which violated the contracts with F&F and U.S., are being returned to them, making THEM, as opposed to you and U.S., pay for their intentional fraud?
How very interesting, of you, to like being swindled.

----------
Jozef:
Your response to the second point is to suggest that you are unaware of the criminal investigations that are ongoing on both the Federal and SEC and local levels. We are not. While we could tell them some horrific stories about WAMU in WA, Cal and AZ, we have no reason to do so, bcuz they already have them. Even if you do not.

If you have not read these "tip of the iceberg" stories, you might find them interesting:Mortgage Lenders Seek Relief on Bad Debt Repurchases
http://www.businessweek.com/news/2010-05-27/mor...
Banks Say No. Too Bad Taxpayers Can’t.
http://www.nytimes.com/2010/06/06/business/06gr...

=========


Did Fannie and Freddie Cause the Housing Bubble?

[mEDITate-OR:
confuse yourselves with unknowable facts...

Daniel is a very good commenter, but he too can make mistakes.
So, when he caught Krugman making one, he pounced.

You will find these two articles to be, truly, wonderful...
if not perfect.

The problem here is that some want to believe what their heart are telling them must be true.
As RonnieR taught all of U.S. - The Govt will not solve our problems, Govt IS the problem.

Then buy eliminating the laws and regulations that DO work...
and cutting back on taxes to force cut in spending on programs that YOU don't like...
we created a self-fulfilling prophesy.

{Y}our Govt has to BE very bad, bcuz we make it so.

==========
JGBell

Very good point, Daniel; but you too missed The Point. But, your graphs show it to U.S. nevertheless.

In 01-03 the GSE were the largest lender, true; but of what KIND of RE loan. In Krugman's 2nd chart that would appear to have been "Prime" RE loans, that were not the original problem loans.  In 04-07 the NAS - NonAgency Securitized - share of the market exploded, according to your chart.  However, in Krugman's chart that was when the AltA & Subprime RE loans also exploded.

So, who DID make all of those 04-06  subprime RE loans...??? In the Sand States of Cal, Nev, Fla & AZ???  And who went BK and were bought out - Countrywide, WAMU & Wichovia.

Are you really saying to U.S. that by making all those 01-03 prime loans the GSE's caused all of the problems? When your own chart shows U.S. that it was the NAS creating AltA and subprime RE loans in 04-7 that did U.S. in.

What you also did not point out was that the GSE, like GD fools, began to sell AltAs and Subprime RE loans towards the very end of the disaster. Late to the party, and like a drunken sailor. While the GSE's were to blame for stupidly jumping in late; they did NOT start or fuel the subprime and AltA problems in the sand state. Nice try, but you are wrong
------------
Did Fannie and Freddie Cause the Housing Bubble?
-----------
Things Everyone In Chicago Knows - Which happen not to be true.
-----------

krugman gses cht1.png

krugman gses cht2.png

nominal mortgage issuance 2010-06.PNG
============

Should you rent or buy? = Trulia's Rent vs. Buy calculator + Most (and least) affordable cities

[mEDITate-OR:
stop questioning your life style assumptions..., economically, of course.

Maybe even to giving up your day jobs...
bcuz, you do see, do you not, that where you live...
while you work and after you retire...
matters..., a lot

But, oddly, what has changed is the price & cost of owning a home.
What is also about to change is the cost of renting.

Bcuz of the RE collapse, single family homes are, in some place, real bargins.

However, what we are also seeing is that the RE loans for apartments, and for the construction of condos, has markedly changed, and will change even more so over the next 2 to 5 years.
There is not money available for buyers of condos, so the builder/lenders have to rent them.

And, with the competition from foreclosures, many apartments RE loans are so underwater, with vacancies, and collapsing land values, that they are being foreclosed on, too.

Rents are now dropping in high foreclosure areas at alarming rates.

--------
Should you rent or buy?
-----------
------------
Here are the 5 metro areas where the average American family can easily afford to purchase a median-priced home - and the 5 where they can't
===========
chart_rent_vs_buy_2.top.gif
==========

Thursday, June 3, 2010

First-time jobless claims drop for second week + Private sector adds 55,000 jobs in May

[mEDITate-OR:
wonder who might be telling U.S. the truth, here...

These reports probably are closer than what we will see tomorrow. When the temp census worker hires are going to be added to the normal numbers. As Jim at CR showed U.S. the census jobs will materially impact the jobs numbers for a number of months - with the larges skewing this month and next.
-------

First-time jobless claims drop for second week
But claims remain at elevated levels, even as employers lift hiring
New claims for unemployment insurance fell for the second straight week, fresh evidence the job market is slowly improving.
----------
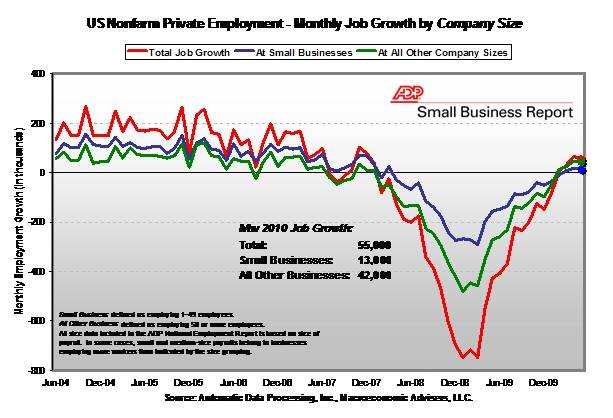
Private sector adds 55,000 jobs in May
April’s report revised from 32,000 to 65,000, according to ADP

Private employers added 55,000 jobs in May, compared with an upwardly revised gain of 65,000 in April, a report by a payrolls processor showed on Thursday.
Job hopes rise on wave of economic data
Reports don't ‘scream strength’ but they do ‘set encouraging tone’

A handful of economic reports released Thursday raised hopes for an improving job market with fewer layoffs and more hiring.
==========

Wednesday, June 2, 2010

Is Massive Refinancing During Bubble Years a Ticking Bomb? = Investors Played a Key Role in Creating

[mEDITate-OR:

not see that both previous, and now future, foreclosures...
occurred in the same, select places and will continue.

These are two MUST READ articles.

What these two article also show U.S. is that MOST of the underwater home owners
already took their paper profits out of their homes..., in cash.

Now, they are going to have to pay some or all of it back.
If they can.

And, if they cannot, the lender/bank that gave them the HELOC will have to eat it.

--------
JGBHimself | 06/02/10 2:55 PM


Very good article - probably the best Jumbo loans data we have seen in over a year. Thanks.
As you point out for U.S., the "Jumbo Loan" problem is huge, not being fixed or addressed, and will materially affect the states that have them.
In a recent AZ Republic article they discovered an interesting other problem - builders are now able to buy fully ready lots for a fraction of what it costs to develop them, or what they were a few years ago. That means that they can now build and sell a new home for from 40% to 60% of what the same home was priced at the peak. All existing sand states home owners - & especially those with jumbo loans - are now being attacked from both sides - foreclosures and now brand new homes.
Could get ugly.
-----------

I didn't include it in my article, but I have California stats for origination of HELOCs since January 2003.

It's incredible.  At the peak in June 2005, 91,000 purchase HELOCs were issued.  That does not include any refis.  

Do you know how many were originated in March of this year?  22 for the entire state.  And 18 refi cash outs ... for the entire state.

The banks have completely pulled the plug on HELOC lending there.  They've also reduced or eliminated the unused credit lines of many current HELOC holders on the grounds that the houses have dropped substantially in value.  Most California borrowers also have a HELOC or second mortgage.  They are really up the creek.  Many were using their lines of credit to pay their mortgage and/or live on.  Not much longer though.
Thanks again. Keith Jurow

=============
Is Massive Refinancing During Bubble Years a Ticking Bomb?
============

Monday, May 31, 2010

Economic Flavor of the Day: Housing, GDP and More

[mEDITate-OR:
miss reading a very good summary of where we all are, this week...
may not cover everything, but tis close.

-----------
May 30 10:59 PM
While we agree with you about Steve's article, it is very good - may we share some "strategic default" thoughts - all SD's were not created equal, and are not now.

If you want to know where SD are most likely to occur, and why; read and answer the following:

See if you can find THESE numbers = the percentage of the Wall Street created securitized RE loans: A. in the "sand states" = Cal, Nev, Fla & AZ; B. during the "dead zone" years - 2002 to 2007; C. of the ARMs created - no doc, liar, interest only, & low down loans; D. of the RE loans "pushed" by WAMU/Chase, Countrywide/BkOAmer, Wells/Wichovia, and IndyMac/BK, and now being written off, very slowly, by them; E. of the total "underwater" RE loans owed by U.S.; and F. as in a failing grade, of the RE loans that have already been foreclosed, PLUS those 10% of all current RE loans that are either IN foreclosure or in a past due status.

-----------
May 30 10:50 PM
First, this statement is half wrong: "Unfortunately, incentives seldom create a new demand but simply time shift the purchase."
While it obviously is true that the start and the end of the Buyer Tax Credit did shift purchases forward twice; the statement that incentive seldom create new demand is, in this case, simply false. The tax credits did drive sales. Some would have bought anyway, true; but many would not have, over the last year, without it. Look at the sales numbers.

Second, you must know that not all of the animals are equal - specifically, that new home builders and strategic defaulters in the Sand States ARE very different - before, during and now after the collapse. You, too, need to read this story: New homes being sold again in distressed Gilbert area @:
www.azcentral.com/news...

Notice: "Developers can buy the finished lots for a fraction of what they sold for a few years ago, and the cost-per-square-foot to build a house has plunged" ! No permits to buy & wait for, no land to develop, no utilities to pay for & install, no amenities to pay for, no or very low upfront costs. Just find a buyer with a pre-approved mortgage to pay for it, and build to their specs.

What THAT means is that existing homes - sold in sand states, during the dead years, and very much underwater..., are NOW being undermined by newly constructed homes as much as they were/are by "foreclosures". THAT probably will force far more walkaways/strategic defaults, bcuz your home will never, EVER be as affordable as these new homes are now. Depressing the AZ housing economy, for years!

May not be true where you are, but in the Sand States it is true.
--------
Economic Flavor of the Day: Housing, GDP and More
==========

========

New homes being sold again in distressed Gilbert area

[mEDITate-OR:
not infill your knowledge about infilling...

Said they:
"Developers can buy the finished lots for a fraction of what they sold for a few years ago, and the cost-per-square-foot to build a house has plunged"
No permits to buy & wait for, no land to develop, no utilities to pay for & install, no amenities to pay for...
no upfront costs.
Just find a buyer with a pre-approved mortgage to pay for it, and build to their specs.
MOG, what fun.

=========


Obviously, very good news, for the builders, the pre-existing home owners in the subdivisions, and the "new home buyers" using the Tax Credits.
However, please notice the sharp decline in new permits.
That, along with the news that purchase mortgage apps declined in May to a 13 year low, might lead some of U.S. to a rather different conclusion.

----------


Also, please note: 
"Developers can buy the finished lots for a fraction of what they sold for a few years ago, and the cost-per-square-foot to build a house has plunged"
What THAT means is that existing homes - sold in sand states, during the dead years, and very much underwater..., are NOW being undermined by newly constructed homes as much as they were/are by "foreclosures".
THAT probably will force far more walkaways/strategic defaults, bcuz your home will never, EVER be as affordable as these new homes are now.
Depressing the AZ housing economy, for years....!
------------
New homes being sold again in distressed Gilbert area

2010 Gilbert residential permit activity
Permits issued (before construction begins)
•  January: 128.
•  February: 132.
•  March: 160.
•  April: 82.
•  May: 65.
-----------

Sunday, May 30, 2010

Arizona commercial real estate brokers: Some lenders ignore crisis = 'Extend, pretend' on bad loans may spell disaster

[mEDITate-OR:
not feel VERY sorry for your BK local banks and S&Ls
they are "damned" if they do, and they are "damned" if they don't...

According to Calculated Risk's list of troubled banks, it is up a lot, again, this month...

So..., "extending" is not just "pretending"..., it is something that they MUST do, to stay alive & in business.

Not just as the Big Bailed Out banks are milking U.S. for every fee they can find to charge U.S., in order to increase their income to cover their losses - both those they have taken AND those they have refused to take....
Small, local, commercial banks are stuck with these bad and non-performing loans.
IF they take the loss, now, the FDIC will close them.
IF they can make some money, or if these Cmcl RE loans recover, they MIGHT survive to live another day.
-----------------
Real-estate brokers believe lenders that are extending loan terms are just simply delaying the inevitable.
Arizona commercial real estate brokers:
Some lenders ignore crisis
'Extend, pretend' on bad loans may spell disaster
The experts said about 25 percent of outstanding commercial real-estate loans are in good shape, and another 25 percent are doomed to foreclosure.
The remaining 50 percent could go either way. It's the fate of those loans that concern analysts.
"That's an aggregate southeast Valley vacancy rate of 35.5 percent, with east Mesa taking the biggest hit at a vacancy rate of 68.4 percent"
==========
Commercial real estate
Commercially challenged: A number of commercial properties and districts in the Valley have struggled to survive the current recession, which experts said stems primarily from overbuilding and risky lending practices. Here are a few examples.
============

Fannie Mae: Rate of late home loans eased in March BUT For apartment building mortgages behind at least 90 days, the delinquency rate is up

[mEDITate-OR:
shift with the blowing winds of time...

If foreclosed homes cannot be sold, but must be rented out or left empty...
If increase home rentals drive apartment prices down...
If declining rents and increased vacancies deprive apartments of income...
they will, eventually, not be able to make their mortgage payments.

Into each life a little rain must fall...

===========
Fannie Mae: Rate of late home loans eased in March
For apartment building mortgages behind at least 90 days, the delinquency rate inched in March to 0.79 percent from 0.73 percent.
============

Arizona could become a hotspot for alternative energy, but new plants won't open without new infrastructure + Biodiesel producers press feds on credit

[mEDITate-OR:
make little or no progress..., here and/or there...
This is an odd couple of stories.

The first article is an extension of the ongoing political debate over "the grid system".
Which is one that we SHOULD address, asap.
More power is lost in transmission TO your homes, than many of U.S. use.
More so in rural and suburban, less dense population areas; but true.
Similarly, we in AZ, and most of U.S., could save more water by re-sealing our old leaking mains and pipes, than we can by damning more streams, or by re-using waste water.
THAT little bit of info is almost never mentioned.
But, if AZ cannot use/produce solar power, who in Hell - aka, AZ - can?

The second article points out the "Great Depression" Phenomenon, quiting doing something before it fully works.
We now know that most of the later and long term harm done by the GD was because Roosevelt stopped stimulating the economy too soon.
This same stupidity is now taking place in alternative energy and in the economy of U.S.
Shifting from corn and soybeans is necessary and economically wise... but, NOT continue to support the conversion of McDonalds and KFC's waste fat into biofuels is incredibly stupid.
----------
Arizona could become a hotspot for alternative energy, but new plants won't open without new infrastructure
Renewable-energy companies from Florida to Spain have their sights on Arizona, submitting applications for more than 80 solar and wind power plants across the state valued at tens of billions of dollars.
If even a fraction of the proposed plants come to fruition, they could bring thousands of construction jobs, manufacturing potential and other economic benefits, including revenue for the Arizona State Land Department, which funds schools. But no more than a few of the plants will be able get their energy to customers without new high-voltage transmission lines.
===========


Let U.S. see, now..., we - you and U.S. - subsidize corn, soybeans, tobacco, cotton, milk, cheese, gasoline (it's called the depletion allowance), but we ought not promote the conversion of grease from our McDonald's and KFC's into a usable fuel. Some might think that strange.
What should NOT have happened is we allowed the corn and soybean lobby/growers to expand their already excessive subsidies into Biofuels. Those two are some of the WORST source products for biofuel. As the Pretty Lady told U.S.: "Mistake..., big mistake!"
However, IF we use the best of the sources, such as a plant grown in the "off seasons" in dry winter wheat crop rotations, we get almost FREE sources; and ALL waste fats now dumped into land fills; and develop "Algae" for U.S. to use; we can actually save ourselves a ton of money.
But, no, you like [y]our government subsidies for private businesses.
Very strange, said Alice.
----------
Biodiesel producers press feds on credit
Biodiesel companies across the nation, including some in Arizona, say their future is at the mercy of Congress, which has been slow to renew a crucial federal tax credit for the industry.
Most biodiesel producers have scaled back production and are in a holding pattern while waiting for Congress to act, and industry production has dropped to about 10 percent of capacity, insiders say.
For six years, the federal government has offered a tax credit to encourage the production of biodiesel, a clean-burning fuel made primarily from used vegetable oil. The incentive gives small biodiesel companies $1 for each gallon of fuel they sell and helps them compete with other sources of energy, which, like oil, are subsidized by the government.
But that tax credit expired at the end of last year, casting the industry into turmoil. In April, the National Biodiesel Board sent a letter urging Congress to renew the incentive or risk the loss of 23,000 green jobs.
==============

Business Books: Why Russia and China will eat your lunch

[mEDITate-OR:
panic..., will run in the streets..., of Boston, too...

What happens when you look at any/all economies through "distorting" glasses...
You "see" what you want to see, and not necessarily what is.

Take merely one example = Iran.

What everybody knows is that Iran has, next to the Saudis and Ruskies...
the worlds largest remaining supply of crude oil reserves.

But, do you KNOW who is buying that fuel from Iran?

And, do you know that Iran has NO refining capacity at all.
ALL of the gasoline they use - cars, trucks, planes...
must be imported.
So..., where does THAT fuel come from?

And, Iran has some of the lowest prices for retail gasoline in the world.
They do not refine it.
They sell crude, then they buy refined product back, and sell it at a loss.

And, we - you and U.S. - call for "sanctions" against them.
Yet, we - you and U.S. - do absolutely nothing about the fuel problem - theirs and ours.

Incredible, but true.

==========
JGBell
May 29, 2010 5:13pm EDT

Market manipulation by "Them" is bad, but when we do it tis not. Oh really?

You, obviously, do not use: the transcontinental railroads, built with Govt money; US ports, built & controlled by Govts; the Interstate Freeway system, built with Govt money; or airlines, with airports build with Govt money and other subsidies.  OR, a "centralized" banking system, like VISA debit/credit cards. Or, a "centralized" medical care system like Blue Cross. Or, a "subsidized/centralized" agricultural system for corn, cotton, oil, etc, for U.S. Or, eat any beef, pork or chickens, produce for U.S. by agra-monopolies.

What Japan learned, from U.S. by the way, was that IF they adopted an "industrial policy" they maximized their economic strengths, they could, and would, be able to dominate certain chosen areas - the one's that they wanted to be, and could be, very good at - ie, more efficient.

That is what China has been and IS doing to U.S.
That is what Russia is doing to dig themselves out of the mess they put themselves in - selling there most valuable resources to robber barons didn't work, either; so they have "nationalized" crude oil and natural gas, and are exporting it to Europe in return for a lot of cash.

Oh, and did you NOT notice that "thing" called OPEC? Of course not. But, IF you did, what, precisely, would you call THAT, in Saudi Arabia?

China and Russia are threatening to U.S., now? OMG. But, glad you noticed it.
-----------
Business Books: Why Russia and China will eat your lunch
(Reuters) - The Western multinationals that have dominated global trade for decades are going to have their lunch eaten in China and elsewhere, and many are unaware it's about to happen.

The Root Cause of the U.S. Housing Bubble Has Yet to Be Addressed

[mEDITate-OR:


-------
Astounding, that on "Memorial Day", one of you write about "no money down" not being home ownership. MOG it is as if we did not win WW2, and did not create the GI Bill for servicemen to return home and be able to buy new homes via VA low down payment loans, and to go to college with Federal funds supporting them.

After the Great Depression, you appear to think that ONLY FMae&FMac were created to promote ownership. As if FHA 3% down home loans did not exist that far back, and still do not today.

What you forgot, or chose to ignore, is the fact that FHA loans were less that 3% of the RE mortgage market immediately prior to the collapse of the " securitized ARM packages" promoted and marketed by Wall Street prior to 2008, And, that FHA last month has grown from less than 3% then to over 50% today - more than FMae&FMac combined. That growth was led/created by the SAME mortgage brokers, builders & real estate salespeople who were marketing ARMs two years before. FHA foolishly permitted those sharks to start originating loans for them, as The Pretty Lady told U.S.: "Mistake, BIG mistake."

Eliminate that bubble, and you can look, if you would, please, at the foreclosure rates for GI/VA loans from after WW2, and for FHA from the beginning. Precisely, how many of THOSE 3% down loans went bad?

May 28 11:49 pm


---------------While your point about the "Investment Bankers" making obscene profits/income was on point, you missed another one.

Prior to WBush's administration, "securitized RE loan packages were a very insignificant portion of the home loan market. However, by their collapse in 2008 they were over 50% of the whole RE mortgage market.

But, even THAT number is mis-representative of the true size of it.

See if you can find THESE numbers = the percentage of their securitized RE loans: A. in the "sand states" = Cal, Nev, Fla & AZ; B. during the "dead zone" years - 2002 to 2007; C. of the ARMs created - no doc, liar, interest only, & low down loans; D. of the RE loans "pushed" by WAMU/Chase, Countrywide/BkOAmer, Wells/Wichovia, and IndyMac/BK, now being written off, very slowly, by them; E. of the total "underwater" RE loans owed by U.S.; and F. as in a failing grade, of the RE loans that have already been foreclosed, PLUS those 10% of all current RE loans that are either IN foreclosure or in a past due status.

What they left U.S. is much worse than what they took for themselves - as hard as that is to believe.
May 29 12:20 am


============
If your charts are cut off, please go to the article for them.
========
The Root Cause of the U.S. Housing Bubble Has Yet to Be Addressed
============